Counterpoint Research has published a launch comparison that reframes how quickly Apple's flagship momentum can build in its most contested market. According to the firm, iPhone 18 Pro China sales during the first three days of availability came in 12% higher than iPhone 17 Pro sales managed across their entire first week a year earlier. Three days against seven. That is the headline, and it arrives less than two weeks after the new models reached Chinese retail shelves.
The figure comes from Counterpoint Research, a mobile market intelligence firm whose quarterly tracking data is routinely cited by manufacturers, carriers, and financial analysts as a benchmark for handset performance. That provenance matters. Launch-week comparisons are among the most closely watched signals in the smartphone industry, precisely because they strip out the noise of long-run averages and isolate initial consumer response. A 12% gain on a compressed timeline is not a rounding error.
iPhone 18 Pro Shatters China Launch Records in Three Days
Three days of sales exceeding a full week of predecessor sales is a difficult result to explain away. Apple's iPhone 17 Pro models had a full seven-day window to accumulate their launch total in China last year. The iPhone 18 Pro matched and surpassed that total by the 72-hour mark, according to Counterpoint's tracking. The implied daily run rate is roughly two and a half times higher, a pace that suggests either a materially larger pool of early adopters, stronger channel fill, or both.
China has long been one of Apple's most strategically complex markets. It is the world's largest smartphone arena by unit volume and the home turf of aggressive domestic competitors across every price tier. Year-over-year launch comparisons have become the standard industry yardstick for reading Apple's standing there, because they control for seasonality, promotional calendars, and the natural decay curve of any product cycle. Against that benchmark, a double-digit gain in the opening days is the kind of data point that moves analyst models.
Counterpoint's numbers also carry weight because the firm tracks sell-through rather than merely shipments into retail channels. A three-day surge measured at the consumer level implies genuine demand rather than inventory loading. That distinction has mattered in past cycles, when channel fill occasionally flattered early shipment data that later had to be worked down through discounting.
The compressed timeline deserves emphasis. A launch weekend concentrates the most committed buyers — upgrade-cycle loyalists, carrier switchers with expiring contracts, and enthusiasts who preorder within minutes. If that cohort alone is 12% larger than last year's full-week base, the broader addressable market Apple is reaching in China has likely widened, not just intensified.
Apple Claims the Top Spot in China's Smartphone Market

The launch surge carried Apple to the top of China's smartphone market for the week of September 14 to 20, according to Counterpoint, with a 33% share of the country. A single week at one-third of the market is a striking position in a country where no vendor typically holds a durable majority and where share leadership often rotates on launch timing alone.
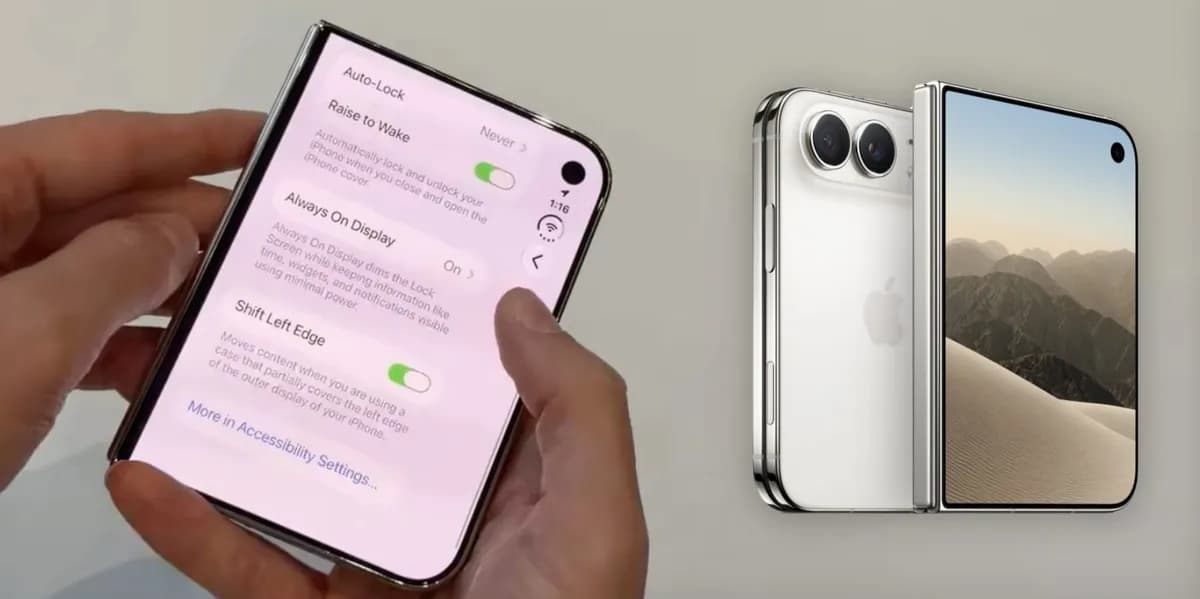
Read next iPhone Duo's Hidden Fake Bezel Setting ExplainedThat 33% figure is the second pillar of the Counterpoint report and arguably the more revealing one. Weekly share leadership in China is frequently decided by who happens to have a fresh device on shelves. The question for Apple is whether this is a launch-week spike or the beginning of a sustained shift. Counterpoint's own framing points toward the former as a baseline expectation, with the October product calendar determining whether the spike extends.
Context matters here. Apple's position in China has been a running debate among analysts for several years, with concerns about domestic competition, regulatory pressure, and lengthening upgrade cycles all cited as headwinds. A week at 33% does not resolve that debate. It does, however, provide a concrete counterweight to the most pessimistic scenarios, and it establishes a high base against which the next several weeks will be measured.
The share number also matters mechanically. Apple's pricing sits at the premium end of the Chinese market, so unit share understates revenue share. A 33% unit position during launch week implies a disproportionately larger slice of the market's total value, because the iPhone 18 Pro's average selling price sits well above the national average. Counterpoint has consistently found that Apple captures a share of industry profit far exceeding its share of units in China, and a launch week at this level will feed directly into that calculation.
Why Demand for the iPhone 18 Pro Is Running Hotter in China
A 12% year-over-year gain in a mature market is not typically the product of a single factor. Chinese consumers have shown a documented willingness to pay for meaningful upgrades, and the premium tier there has proven more resilient than the mid-range, where domestic brands compete most aggressively on price. Apple's installed base in China is also substantial, which means small shifts in upgrade propensity produce large absolute unit movements.
Timing plays a role as well. The comparison here is against iPhone 17 Pro's first week, not against a soft period. That makes the gain a like-for-like measurement against an already solid baseline, which strengthens the signal. Counterpoint's methodology of comparing equal launch windows — three days against seven is the comparison the firm drew — is the kind of apples-to-apples framing that analysts prefer over raw sequential totals.
There is also a channel dimension. Apple's retail and carrier partnerships in China have expanded over successive cycles, and launch logistics have improved. Faster availability across online and offline channels compresses the window in which demand converts to sales. Some portion of the three-day outperformance may reflect supply reaching buyers more quickly rather than a larger total pool of buyers, a nuance worth holding onto when interpreting the full-cycle numbers that follow. Counterpoint's subsequent weekly and monthly reports will clarify how much of the early surge was pull-forward versus genuine expansion.
The iPhone Duo Factor: October 23 Could Push Apple's Momentum Even Higher
Apple's next China catalyst has a date. The iPhone Duo goes on sale October 23, and the country's appetite for foldables is materially stronger than the global average. That is the structural setup Counterpoint's launch data sits in front of, and it explains why the firm framed the iPhone 18 Pro result as possibly the beginning rather than the peak of Apple's autumn in China.
Foldable adoption in China has outpaced most Western markets for years, a pattern Counterpoint and other tracking firms have documented repeatedly. Chinese buyers have shown greater willingness to experiment with new form factors, and domestic manufacturers have seeded the category with a steady cadence of book-style and flip-style devices across a wide price band. The result is a consumer base that is already foldable-literate. Apple does not have to educate the market on why a folding phone is useful; it has to convince existing foldable owners to switch ecosystems, a fundamentally different and generally easier sales problem.
That distinction is central to the iPhone Duo's opportunity. In markets where foldables remain a novelty, launch demand tends to be enthusiast-driven and narrow. In China, the addressable audience includes mainstream buyers who have already accepted the form factor. The iPhone 18 Pro's strong opening suggests Apple's brand pull is intact heading into that launch. If the two data points compound — a hot flagship cycle followed three weeks later by a category where Chinese demand runs above global norms — Apple's fourth-quarter position in the country could look considerably different from the cautious consensus entering the season.
The risk cuts both ways. A new form factor invites scrutiny on durability, software maturity, and price, and Chinese reviewers are exacting. A well-received iPhone Duo would extend the September momentum into November. A mixed reception would leave the iPhone 18 Pro to carry the quarter alone.
What the Strong Start Signals for Apple's China Strategy Going Forward
The counterintuitive reading of Counterpoint's data is that the most important number is not 12% or 33% but the gap between the iPhone 18 Pro's three-day total and the iPhone 17 Pro's seven-day total. That gap measures acceleration, and acceleration is what determines whether a launch week becomes a launch quarter. Apple entered this cycle needing evidence that Chinese demand for its premium tier had not structurally eroded. Three days of sell-through data, sourced to a firm whose numbers move analyst models, is early evidence that it has not.
What happens between now and October 23 will set the frame for the iPhone Duo. If weekly share holds anywhere near the 33% Counterpoint recorded for September 14 to 20, Apple heads into its foldable launch with unusual momentum in its most contested market. If it decays along the normal post-launch curve, the Duo carries a heavier load. Counterpoint's next update on iPhone 18 Pro China sales will be the first real test of which path this cycle takes — and it will arrive before the Duo's first weekend is even tallied.