Rivian R2 Pays Off: Q3 2026 Sales Surge 85% as the H1
Rivian's Q3 2026 Numbers Tell a Compelling Story
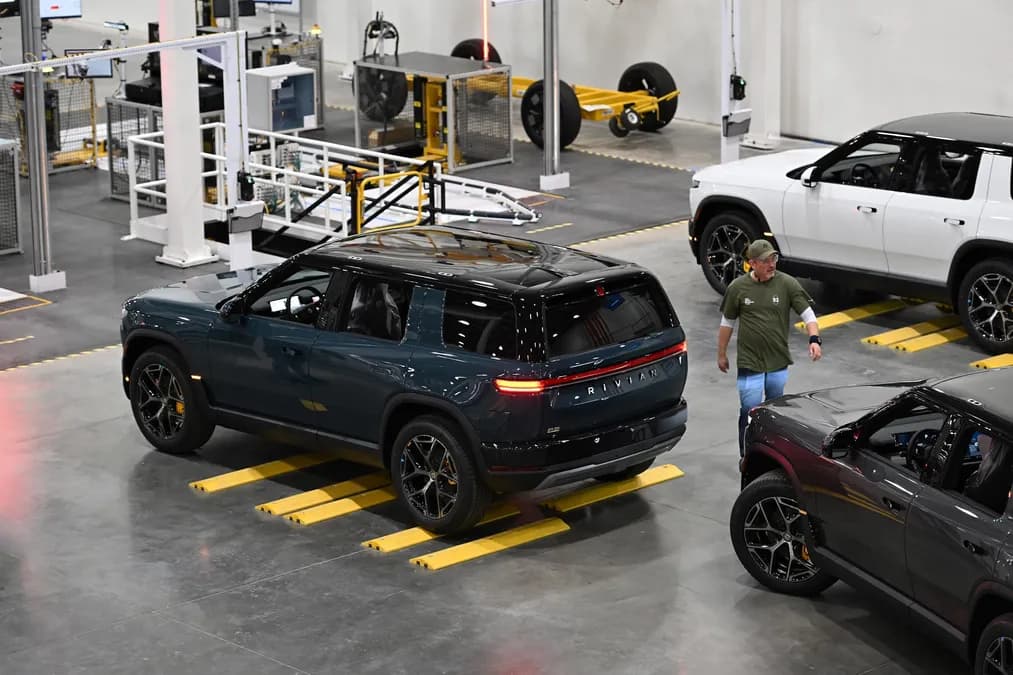
Rivian produced 19,751 vehicles in the third quarter of 2026 and delivered 19,248 of them, according to figures the company released on October 2. The 503-unit gap between what rolled off the line and what reached customers amounts to roughly 2.5 percent of quarterly output — a spread tight enough to suggest that demand is absorbing supply rather than lagging behind it.
Read next Laika's Wildwood: Stop-Motion Fantasy at TIFF 2026That ratio matters more than it might appear at first glance. Automakers routinely build ahead of demand to fill dealer lots, buffer logistics, and smooth factory scheduling. When production and deliveries track that closely, the inventory pipeline is doing its job without swelling. For a company that spent its early years fighting manufacturing bottlenecks and investor skepticism about whether it could scale at all, a 97.5 percent production-to-delivery conversion in a single quarter is a meaningful operational milestone.
The headline numbers are just as striking. Production rose 85 percent year over year, while deliveries climbed 45 percent. Those two figures tell different stories, and the distance between them is where much of the analysis belongs. Production growth outpacing delivery growth typically reflects a manufacturer ramping a new line or bringing a new model online — in this case, the R2, Rivian's more affordable vehicle and the centerpiece of its effort to move beyond the premium tier.
Why the R2 Is Central to Rivian's Growth Strategy
Rivian built its reputation on the R1T pickup and R1S SUV, vehicles that earned praise from reviewers and buyers alike but carried price tags that confined them to the luxury segment. That positioning worked as a proof of concept. It could not work as a volume business.
The R2 changes the math. By targeting a lower price point, Rivian opens itself to a far larger pool of potential buyers — the same mid-market customers who have driven adoption for Tesla's Model Y and the growing field of compact electric crossovers. Rivian had high hopes for the R2, and the Q3 numbers represent the first hard evidence that those hopes are translating into orders.
The strategic logic runs deeper than unit economics. A lower-priced vehicle spreads fixed costs across more units, improves factory utilization, and gives Rivian a product that can compete in the segments where the bulk of EV growth is actually happening. Premium electric trucks and SUVs remain a niche. Affordable electric crossovers are where the volume war is being fought, and Rivian now has a credible entry.
BloombergNEF and the International Energy Agency have both documented the same pattern in global EV markets: growth is increasingly concentrated in lower price brackets as battery costs fall and more models reach showrooms. A company without a competitive offering in that bracket risks being sidelined as the market matures. The R2 is Rivian's answer to that structural problem.
Year-Over-Year Growth: What 85% Production Increase Really Means
An 85 percent year-over-year production increase is a large number, but its significance depends on the base it is measured against. Rivian was still in the early stages of scaling in 2025, which means percentage gains of this magnitude are easier to achieve than they would be for an established automaker producing millions of vehicles annually. Context matters when reading growth rates, and this one deserves to be read with that caveat in mind.
Still, the direction of travel is unambiguous. Production accelerated faster than deliveries, which is consistent with a factory ramping a new model. Deliveries grew 45 percent — slower, but from a larger base. Both figures point the same way: Rivian is selling more vehicles than it did a year ago, and it is building them faster.
The production-delivery gap deserves a second look. A 503-unit spread across roughly 19,750 vehicles implies that whatever inventory Rivian is holding sits close to the factory gate rather than accumulating in unsold stock. Inefficient demand or logistics problems tend to produce wider gaps. Supply chain difficulties — the kind that plagued Rivian in its earlier years — show up as production shortfalls relative to plan, not as deliveries failing to keep pace with output. Neither pattern appears in these numbers.
Equity analysts covering Rivian, including teams at firms like Wedbush and Morgan Stanley, have consistently framed the R2 ramp as the pivotal variable in the company's investment case. The reasoning is straightforward: a successful R2 launch improves gross margins, reduces reliance on expensive flagship models, and gives Rivian a path to the production volumes that make fixed costs manageable. Q3 offers early support for that thesis, though a single quarter is not a trend.
Rivian vs. the Broader EV Market in 2026
Global EV sales have continued to expand in 2026, but the pace varies widely by region and segment. The IEA's annual EV outlook has tracked steady growth in overall adoption, with China accounting for the largest share of new electric vehicle sales and Europe and North America growing more modestly. Sector-wide growth rates in mature markets have generally landed in the double digits — well below Rivian's 45 percent delivery increase.
That comparison flatters Rivian, and it should be treated carefully. A small manufacturer growing from a low base will almost always post higher percentage gains than a market that already sells millions of units a year. Tesla, GM, and Hyundai all operate at scales where 45 percent annual growth would be extraordinary. Rivian is not competing on absolute volume yet. It is competing on trajectory.
Where the comparison is useful is in showing that Rivian's growth is not merely a function of a rising tide. If the broader North American EV market is expanding at a mid-teens rate and Rivian's deliveries are growing at 45 percent, the company is gaining share, not just floating upward. That distinction matters for anyone assessing whether the R2 launch is genuinely resonating with buyers or simply benefiting from a favorable market.
The pricing strategy behind the R2 appears structurally sound for the same reason. A vehicle positioned below the R1 line addresses the segment where price sensitivity is highest and where government incentives, where available, stretch furthest. It also puts Rivian in direct competition with established players — a harder fight than the premium niche, but a larger prize.
What These Results Signal for Rivian's Long-Term Outlook
Cash flow and margins will ultimately determine whether Rivian's R2 bet succeeds, and Q3 deliveries alone cannot answer that question. What the quarter does show is that the company can build a new model at scale and move it into customers' hands without the delays and quality problems that marked earlier launches.
The tight production-delivery spread is the most operationally meaningful detail in the report. It suggests that Rivian's supply chain and logistics operations have matured to the point where output translates efficiently into revenue. For a manufacturer still working toward sustained profitability, that efficiency is not a minor footnote — it is the difference between growth that strengthens the balance sheet and growth that consumes cash.
Analysts will want to see whether the R2 ramp sustains through subsequent quarters and whether gross margins improve as volumes rise. One quarter of strong deliveries establishes momentum. Several quarters establish a pattern. Rivian's investors have waited a long time for evidence that the company can convert its engineering reputation into a durable business, and Q3 provides the clearest sign yet that the R2 is the vehicle capable of doing it.
Key Takeaways for EV Buyers and Investors
For buyers, the R2's arrival at meaningful volume means a more affordable electric option from a manufacturer with a track record on vehicle quality, backed by a production system that appears to be functioning. For investors, the 45 percent delivery increase and the narrow production-delivery gap are the two figures that matter most — one shows demand, the other shows execution.
The 85 percent production jump signals capacity. The 19,248 deliveries signal absorption. Together, they suggest Rivian's pivot toward the mainstream market is working, at least in its opening phase. Whether that holds through the next several quarters will determine if the R2 becomes the foundation of a sustainable automaker or simply a promising start.
Source: The Verge